astronaut
 Pearl
 Zcash
 Walrus
 NEAR Protocol
 Starknet
 Pudgy Penguins

Sam Bankman-Fried (SBF), the former FTX CEO now serving a 25-year sentence, has stirred controversy with a new claim. SBF’s account, managed by one of his friends. posted a memo on October 31, 2025. The caption said, “This is where the money went.”
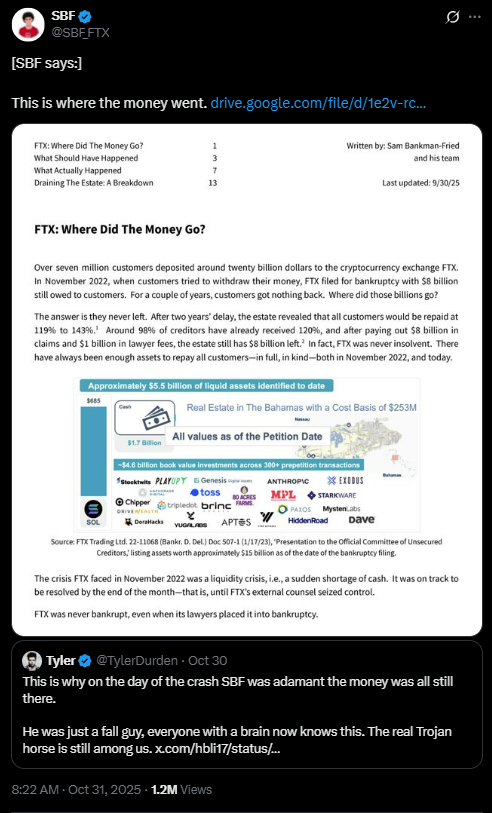
In the memo, SBF asserted that FTX was never insolvent during its 2022 collapse. He says customer assets remain on the platform. Creditors are receiving repayments ranging from 119% to 143% of the original amount. This has sparked debates online and in the crypto world.
What SBF Claims About FTX
SBF argues that FTX held sufficient assets to cover all liabilities as of November 2022. He says the exchange had $93 billion in assets against $15 billion in debts. He claims the $8 billion owed to customers never left the platform.
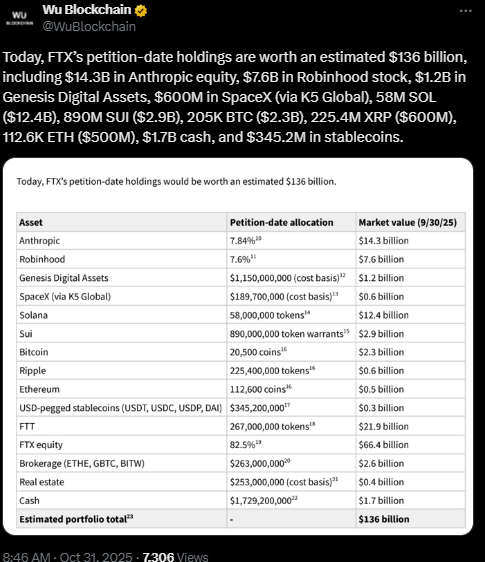
According to a post by @WuBlockchain, FTX’s estate now holds $136 billion in assets. This includes $14.3 billion in Anthropic equity and $12.4 billion in Solana tokens. SBF states that 98% of creditors have already received 120% repayment.
He adds that after paying $8 billion in claims and $1 billion in legal fees, $8 billion remains. He calls the collapse a liquidity crunch, not insolvency. This means FTX couldn’t meet withdrawal demands, but it had overall assets.
Web data supports some of his numbers. Reuters reported that FTX’s bankruptcy plan allows repayment with $16.5 billion in recovered assets. The Guardian noted that $7.3 billion of the missing $8 billion was recovered by April 2023.
However, these recoveries came after the collapse, not before. SBF’s memo suggests that the bankruptcy was mishandled by lawyers, including John Ray III. He blames them for destroying value through rushed sales.
The Counterarguments and Criticism
Many experts and users disagree with SBF. ZachXBT, an on-chain investigator, says creditors were repaid based on November 2022 prices. This caused big losses for holders of assets like Solana and Bitcoin.
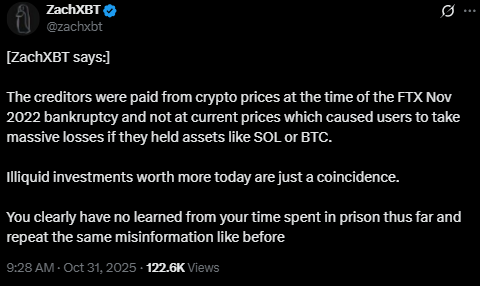
He argues that today’s high asset values are a coincidence, not proof of solvency. The Guardian reported that $11.3 billion in customer funds were missing due to Alameda Research’s misuse. Only $2.3 billion was found. This shows a clear shortfall at the time of filing.
John Ray III, FTX’s bankruptcy trustee, called SBF’s actions a “colossal fraud” in court. He said customer funds were misappropriated for investments and real estate. Wikipedia notes SBF’s past misleading statements, like “FTX is fine” in November 2022.
These were proven false. Critics argue that SBF’s current claims overlook the $8 billion gap that existed when FTX filed for bankruptcy. They argue he is rewriting history to avoid blame. Some X users refer to this as a technical trick, rather than a defense.
The court approved a repayment plan in October 2024. It prioritizes customers over fines. However, it confirms that assets were lost during the collapse. Repayments now reflect market growth, not SBF’s management. This weakens his solvency argument.
SBF’s Pardon Speculation Stirs Amid the Memo Release
SBF’s claims could have big effects. Some supporters, like @wiseadvicesumit, suggest the $FTT token might rise if he’s pardoned. Trump’s recent pardon of Changpeng Zhao fuels this hope.
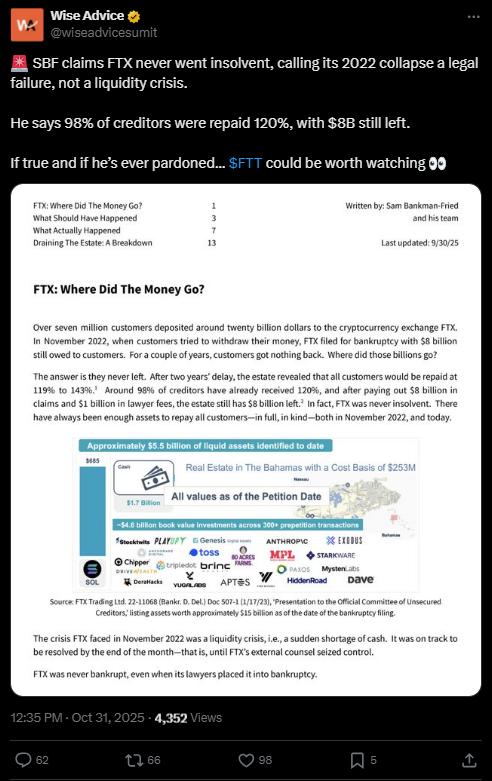
Pardon odds for SBF jumped 6% on Polymarket after that news. However, his conviction is based on solid evidence. The U.S. government says he lives in a “fantasy land,” per The Guardian.
The crypto market watches closely. FTX’s recovery shows how assets can rebound. But it also highlights risks of centralized exchanges.