Dacity Coin
 Zcash
 Sui
 Injective
 Quantus
 Pearl
 NEAR Protocol
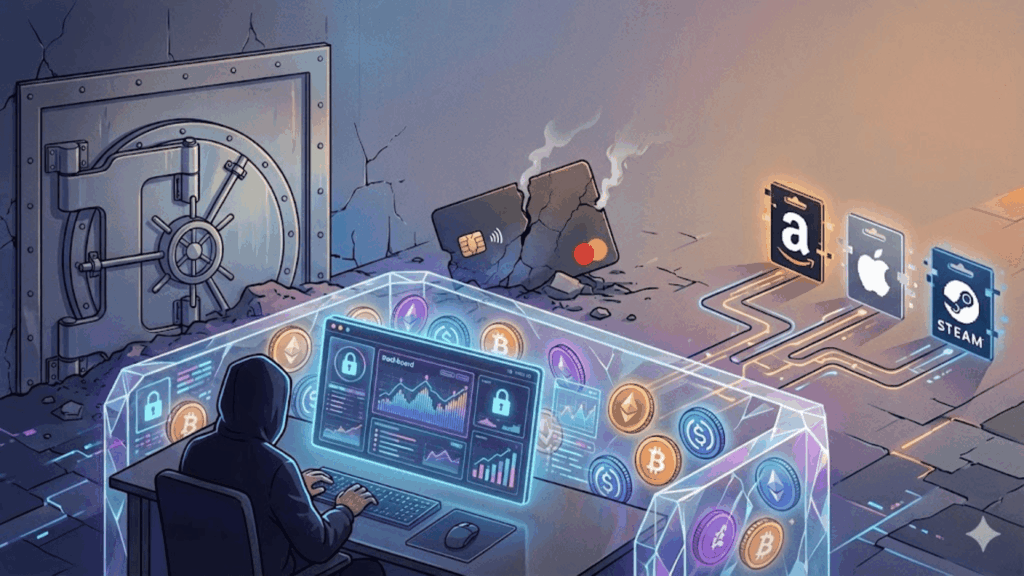
- The “Unbanked” Wealthy: High-net-worth DeFi users are finding themselves effectively “soft-banned” from traditional banking due to source-of-funds scrutiny.
- Card Failure: Crypto debit cards (Visa/Mastercard rails) are proving unreliable due to sudden issuer shutdowns and aggressive KYC demands.
- Direct-to-Merchant: A growing cohort is bypassing fiat conversion entirely, opting for digital value transfer via aggregators.
The “Paper Millionaire” Paradox
There is a growing divergence in the crypto market between “Asset Value” and “Spendable Liquidity”. As the regulatory noose tightens around banking on-ramps, veterans holding significant value in self-custody (Ledger, Trezor, Gnosis Safe) face a new dilemma: the money is yours, but only as long as it stays on the blockchain.
Attempting to move substantial liquidity into a traditional checking account now triggers a compliance gauntlet, possibly freezing capital for weeks. This has created a class of “Paper Millionaires”. These are users with seven figures in crypto, struggling to pay for a hotel room without triggering a bank audit.
The Failure of the “Crypto Debit Card”
For a long time, the industry solution was the crypto debit card. Companies promised a seamless bridge: swipe your card, spend your Bitcoin.
In practice, this model is failing. The underlying banking partners for these cards are under immense pressure. That’s leading to sudden program closures (as seen with recent issuer collapses) or invasive “re-verification” requests.
Crypto-linked card options shrank drastically by late 2024 and into 2025, with only a handful remaining active. Some cards removed crypto features entirely. Other programs have closed specific regional offerings or were wound down due to cost, compliance, or low usage.
Furthermore, these cards destroy the primary value proposition of crypto: privacy. Every coffee bought with a KYC’d crypto card creates a permanent, doxed link between the cold storage and real-world identity.
The Rise of Bearer Asset Spending
Consequently, the smart money is shifting tactics. Rather than trying to turn crypto into fiat, they are looking for ways to spend the crypto as crypto.
This behavior is driving volume toward non-custodial aggregators. These are platforms that treat digital assets as bearer instruments rather than custodial deposits. CoinsBee has emerged as a functional example of this utility. It allows users to route stablecoins or major alts directly into vendor-specific credit (Amazon, Apple, Steam) without a signup process that demands a passport scan for a $50 purchase.
It is a retreat from the “seamless integration” dream, but a step toward reliability. By purchasing store credit directly, users effectively swap one digital ledger (blockchain) for another (merchant database), completely skipping the banking settlement layer.
The Cost of Autonomy
This approach, however, forces a confrontation with market reality: autonomy is expensive.
When you bypass the banking rail, you lose the efficiency of the interbank exchange rate. Direct-to-goods services often bake a spread into the transaction price. A user might pay $102 in USDC to get $100 in purchasing power.
For the retail speculator, this 2% “friction fee” is annoying. But for the crypto native trying to live on-chain, it is simply the cost of doing business and is not so much off from the extra $1 transaction fees for offramps that exchanges charge.