Pearl
 Zylo Ecosystem
 Starknet
 Walrus
 Sui
 Bitway
 Pons

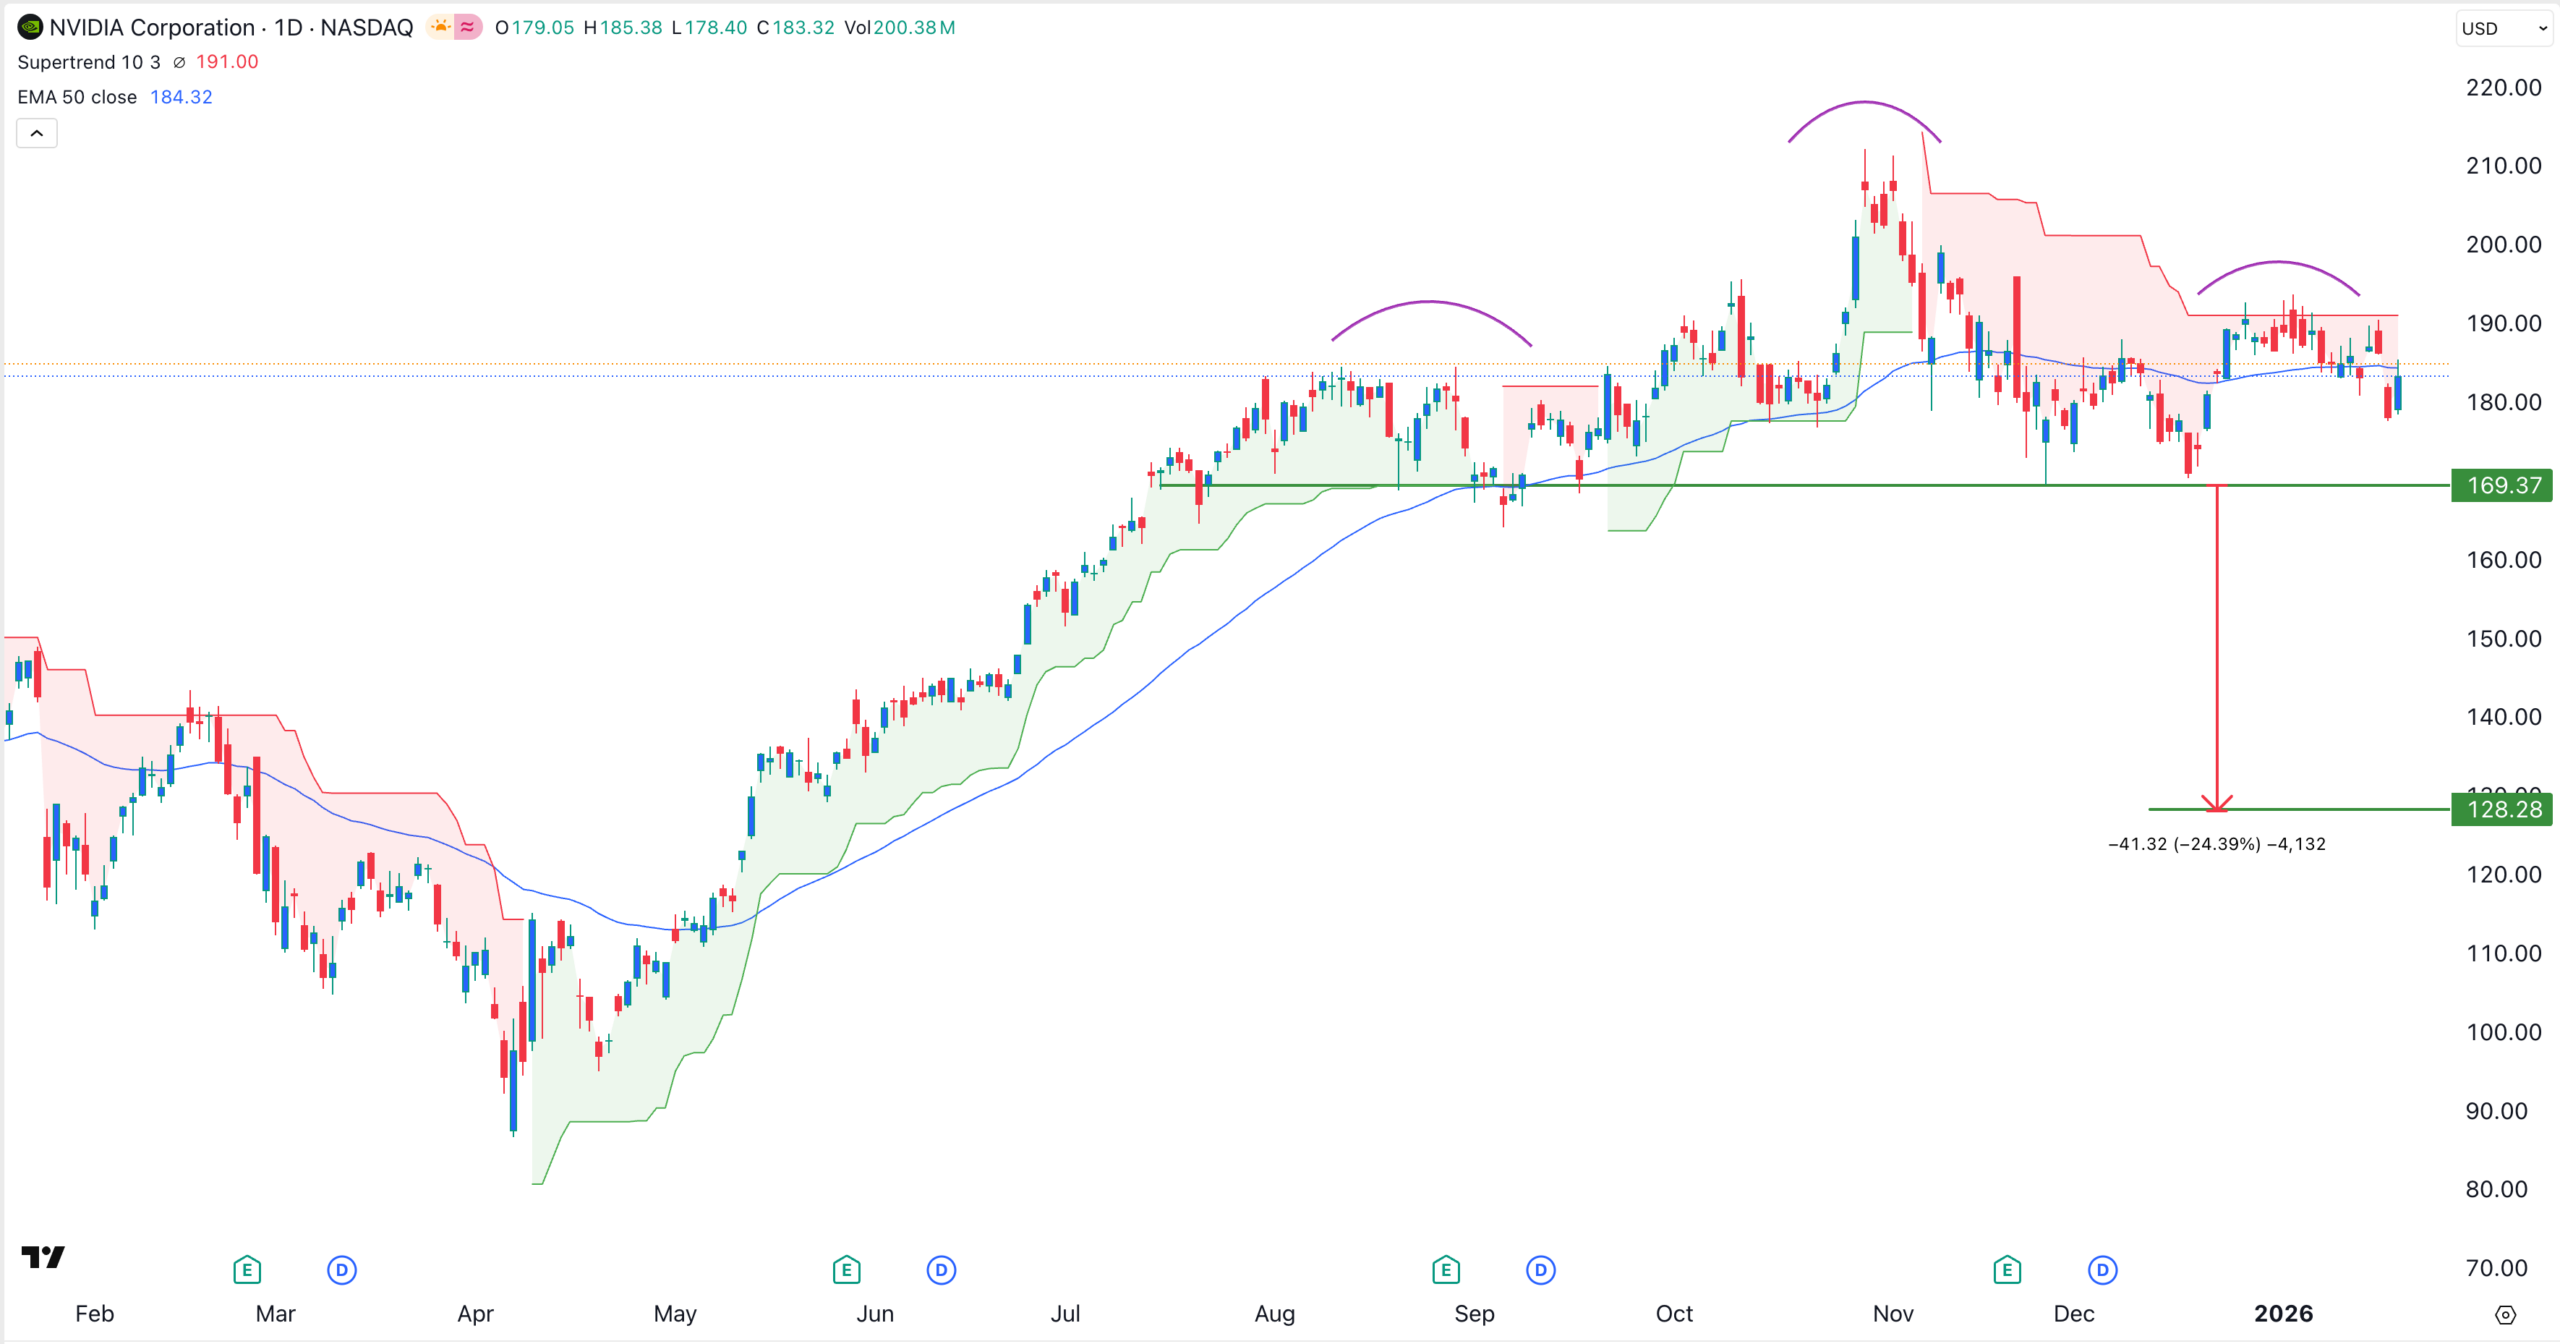
NVIDIA stock price has dropped and moved into a correction after dropping by over 11% from its highest level in October last year. This drop has brought its valuation metrics to its lowest level in years. There are substantial risks that the NVDA share price may continue to fall, potentially to $128 before rebounding.
NVIDIA Stock Price Head and Shoulders Pattern Points to a Crash
The first main risk facing the NVDA stock price is that it has formed a head-and-shoulders pattern on the daily chart. This pattern is made up of a head ($212), shoulders ($190), and a neckline at $169.
The distance between the head and the neckline is 25%. Measuring the same distance from the neckline means that the stock will drop towards the key support level at $128.
NVDA stock shows other bearish signs, including moving below the 50-day Exponential Moving Average (EMA) and the Supertrend indicator. In most cases, an asset tends to drop further when it is below these indicators.
Rising Competition is a Major Risk to NVIDIA
The other main risk that NVIDIA stock price faces is that competition is rising in the data center industry.
AMD has already achieved 10% market share in the GPU industry, and more companies may start to take market share.
Over 10 Chinese companies are working on semiconductors. One of the most prominent is Moore Threads, founded by a former NVIDIA employee. Its stock has surged by over 500% since it went public in December last year.
Other Chinese companies developing similar products include Cambricon, Huawei, MetaX, Biren, and Baidu. These companies will likely take market share over time.
On the positive side, NVIDIA has some advantages over potential new competitors. For example, it has the Compute Unified Device Architecture (CUDA) software, which helps developers to transform GPUs to be used for general purpose roles. Also, the company is in a pole position in the GPU industry.
Customer Concentration is a Major Risk
Additionally, NVIDIA stock faces the risk of customer concentration as it depends on just a handful of clients. Microsoft, a top American company, is believed to account for 20% of its total sales.
The other top clients are hyperscalers such as Amazon, Meta Platforms, Google, and Oracle. These companies account for over 50% of its total sales. Other top clients are companies like Nebius, IREN, and CoreWeave
Therefore, there is always a risk that at least one company may slow its AI data center investments, a move that would impact its business.
Additionally, there is a risk of circular investments, in which NVIDIA invests in companies that then become clients, boosting its revenues.
However, on the positive side, analysts believe NVIDIA’s business will continue to do well, with revenue expected to grow by 50% this year.
NVIDIA Faces Some Major Chinese Risks
NVIDIA faces a major risk in accessing the Chinese market, which is the industry’s largest. Reports show that the company has received over 2 million chips orders from Chinese companies.
However, China has reportedly blocked these chips as it seeks to grow its local industry. As a result, Jensen Huang, the country’s CEO, is said to be traveling to China to talk with its leaders on allowing these chips.
Summary
NVIDIA stock price is at risk of more downside because it has formed a head-and-shoulders pattern. It also faces customer concentration, rising competition, and Chinese risks. The company could also be at risk of the upcoming AI bubble bursting.
However, on the positive side, the company’s valuation has become a bargain. Also, its revenue and profitability growth has accelerated, while its share repurchases are growing. These catalysts may help to offset its decline in the near term.