Wisp
 Doge Pepe
 Crawlerpad
 Zylo Ecosystem
 Pearl
 Basic Attention
 Quantus

Tesla stock remained near $379 on Oct. 6 after extending a recovery from its summer lows.
The rebound followed stronger-than-expected third-quarter vehicle deliveries and renewed interest in Tesla’s autonomous-driving and robotics businesses.
However, Goldman Sachs stopped short of turning bullish on the shares. Analyst Mark Delaney maintained a Neutral rating and a $360 price target.
Goldman Sachs Has Upgraded Tesla Stock
TSLA stock has rebounded since August and this trend may continue. In a statement this week, Goldman Sachs reiterated its bullish outlook for the company, placing its target price to $378, modestly higher than the current $360. Mark Delaney, the analyst, said that the company’s sales will continue rising.
At the same time, the analyst maintained that its other initiatives, including its robotaxis, full self-driving, and humanoids, may boost its business in the long term.
In addition to Goldman Sachs, other analysts have a bullish outlook for the company. Colin Langan, a Wells Fargo analyst, reiterated his buy rating, while Cantor Fitzgerald maintained its overweight rating. Other top analysts with a bullish outlook on the company are from JPMorgan, Royal Bank of Canada (RBC), and BMO.
Its recent delivery report showed that Tesla delivered 486,000 vehicles last quarter after making 464,000. These deliveries were lower than those it sold in the same quarter last year. Last year’s growth was driven by the rush to buy ahead of the expiry of the federal tax credit.
The company may benefit from the ongoing US-Iran war that has pushed gasoline and diesel prices higher. The average gasoline price has moved to $4.36, while diesel has jumped to $6.32 a gallon. As such, many Americans may begin to embrace electric cars, which are cheaper to maintain.
Analysts Predict Steady Growth
Top analysts believe that Tesla’s business will continue growing in the coming years. The upcoming earnings, which will come out later this month, is expected to show that its revenue was largely unchanged at $27.9 billion. This slow annual growth is mostly because of the growth experienced in Q3’25 before the expiry of the tax credit.
Despite this, analysts expect the annual revenue to be $106.7 billion, up by 12.60% from what it made last year. It is expected to jump by 13.54% to over $121 billion. Its earnings per share are expected to continue growing in this period. This growth will be because of its EV and energy businesses.
The key challenge, however, is that its Chinese business continues to face intensifying competition. Indeed, most Chinese stocks, including popular names like Nio, BYD, Li Auto, and XPeng, have all slumped by double digits in the past few months.
Another challenge is that the company’s free cash flow will remain negative as it continues to invest in its giant semiconductor plant in Texas.
Tesla Stock Price Technical Analysis
The daily chart shows that the TSLA stock price has rebounded from a July bottom of $297 to the current $381. Most recently, it formed a small hammer candle on September 30th this year. This pattern explains why it has rebounded in the past few days.
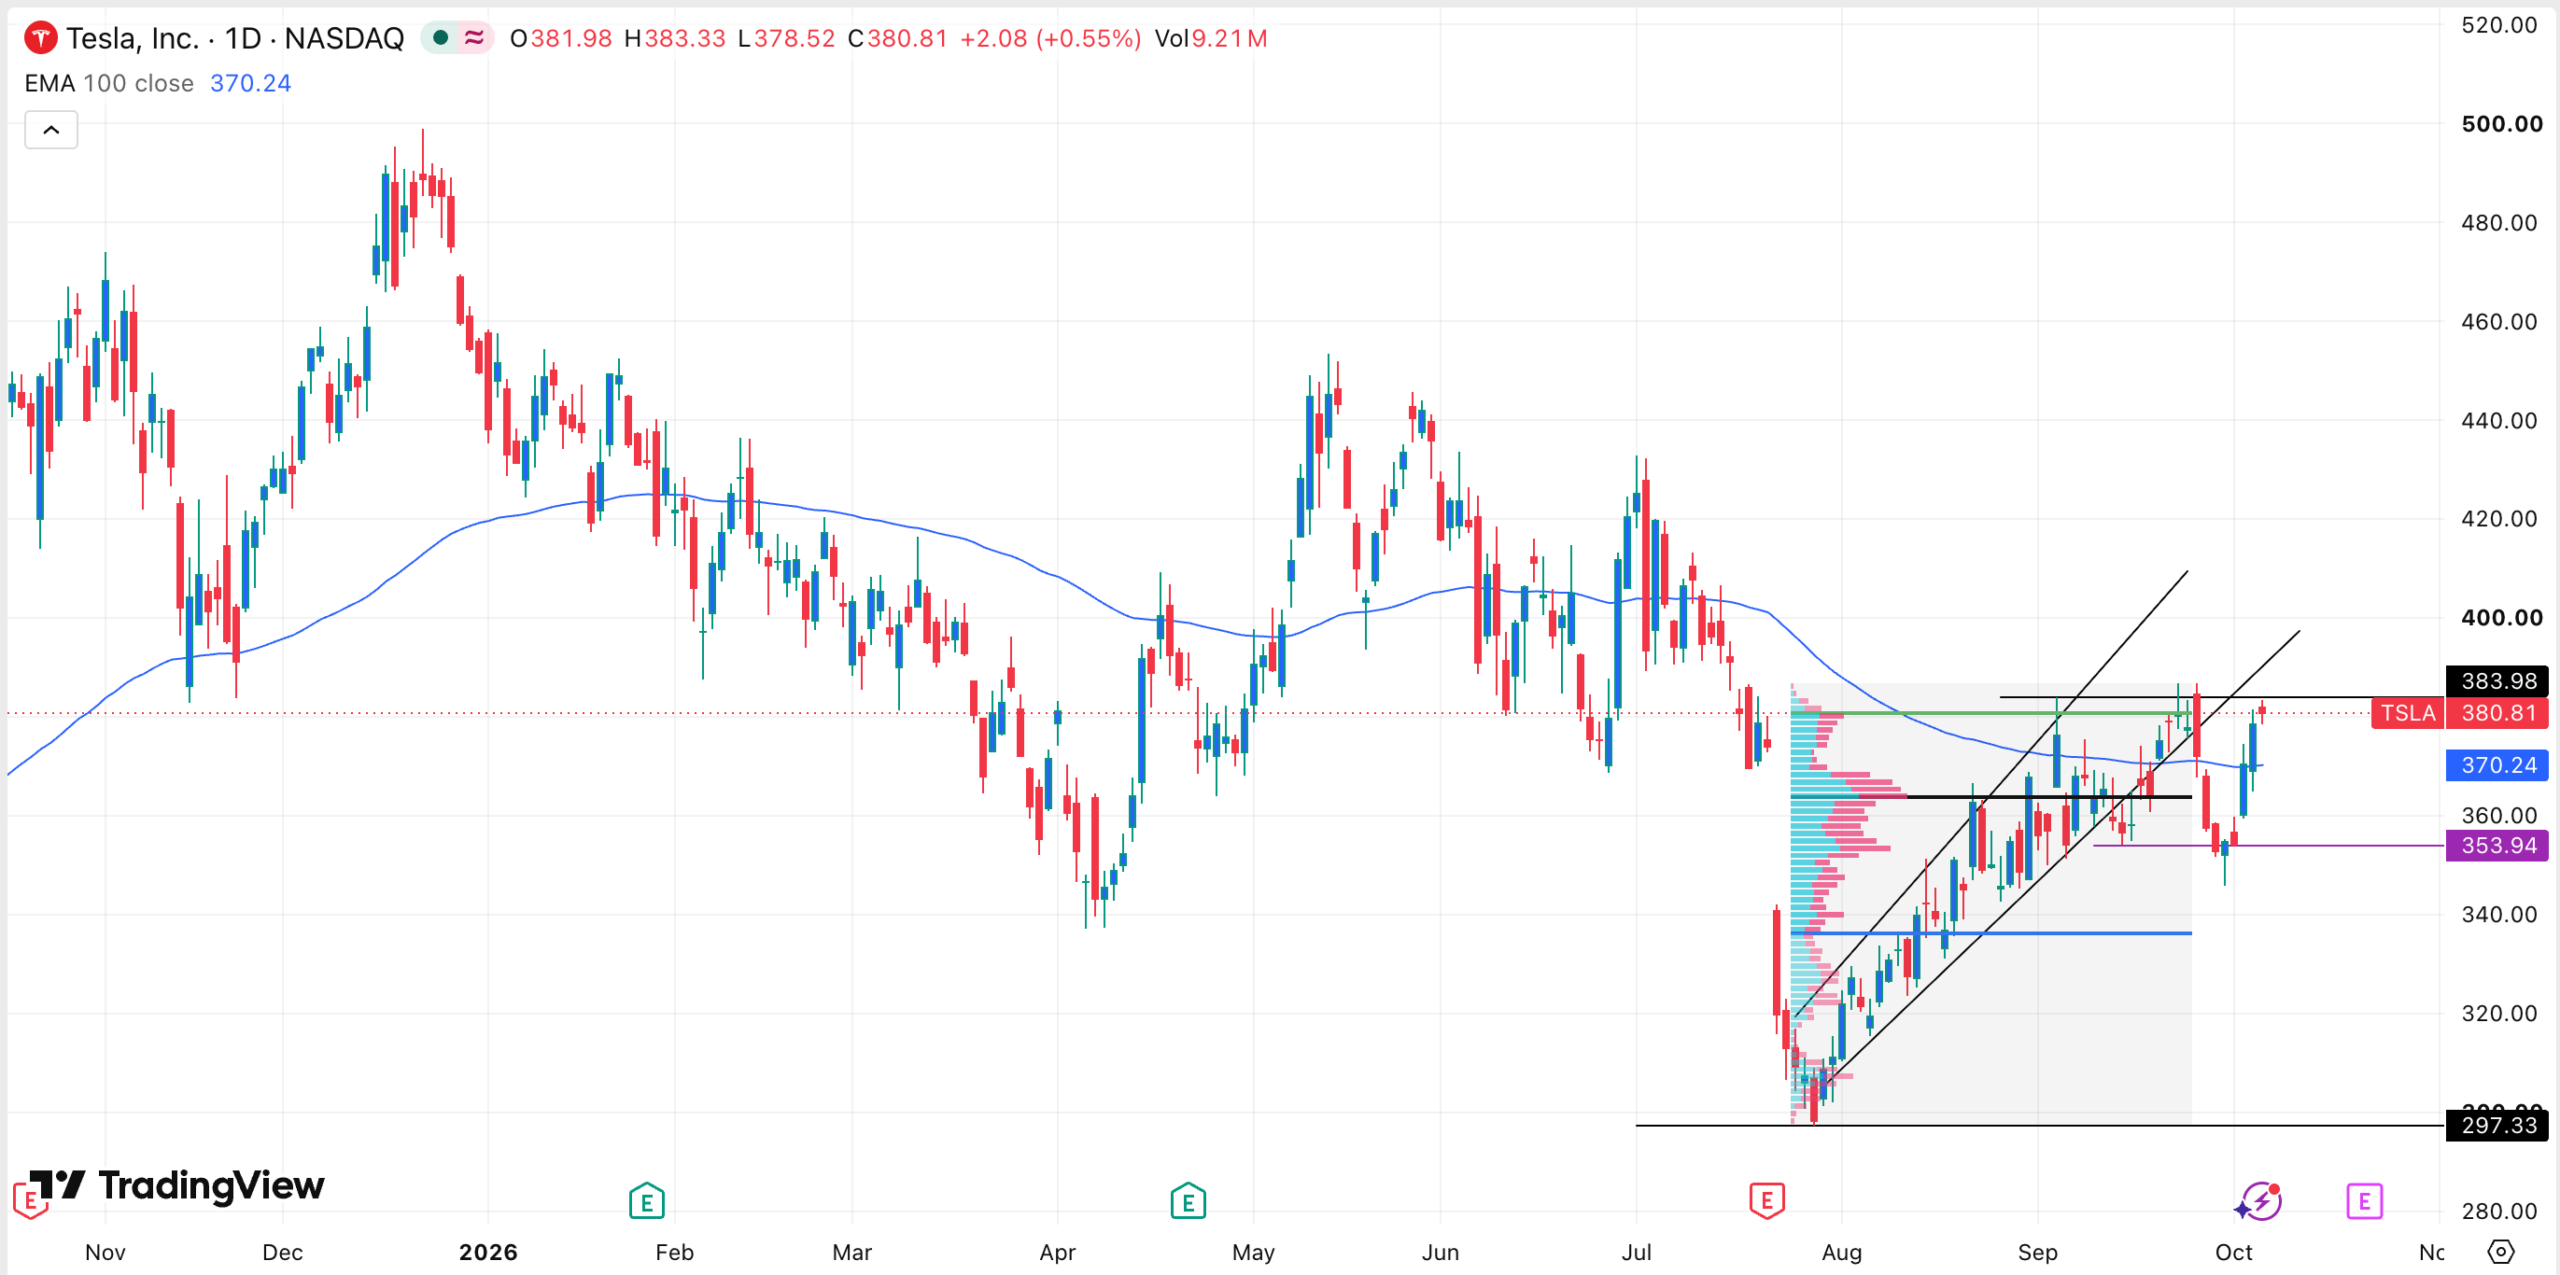
The stock has jumped above the 100-day moving average and $364, the Point of Control (POC) level of the Fixed Range Volume profile. In most cases, moving above that level indicates that bulls are gaining momentum.
The Relative Strength Index (RSI) and the MACD indicators have also continued rising. Therefore, the stock will likely continue rising as bulls target the psychological level of $400.
This article is for informational purposes only and does not constitute financial or investment advice. Analyst targets, technical levels and earnings estimates may change as market conditions evolve.