Sword Inu
 no crying in the casino
 streamoors
 IGNITION
 Altai the Tiger
 Pearl
 Quantus

Goldman Sachs and UBS have raised their Meta stock price targets above $850 while maintaining Buy ratings on the shares. The revised forecasts reflect Meta’s plans to diversify its artificial intelligence offerings and explore new revenue streams beyond the advertising industry.
Goldman Sachs and UBS Raise Meta Stock Price Targets
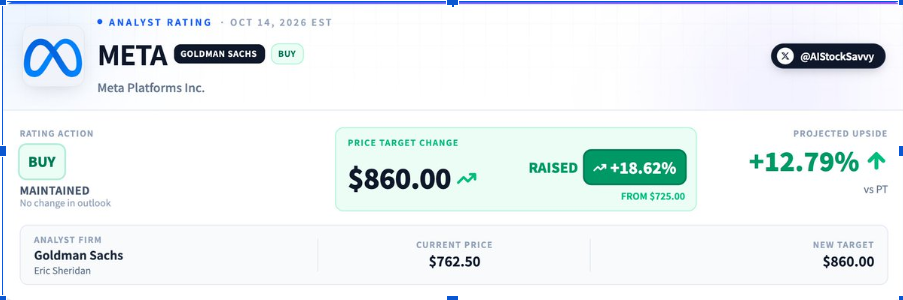
Goldman Sachs analyst Eric Sheridan has recently raised his price target for Meta from $725 to $860, leaving his rating unchanged at Buy. At the same time, UBS analyst Stephen Ju raised its target to $884 from $715 and retained its Buy rating.
For UBS, much of the attention is on Meta’s plans to earn money from its newer AI products. The bank identified Business Agents and Muse as possible revenue sources, particularly through WhatsApp and Messenger.
In addition, UBS believes that Meta could be a contender for search advertising dollars. The company’s latest ad test showed higher levels of funding from automated campaign tools and AI-driven recommendations. As a result, the bank expects these developments to help Meta attract more advertising spend.
The analyst revisions come after earlier Meta stock gains linked to Muse AI adoption, which attracted fresh attention from Wall Street.
Meta Stock Performance and Other Wall Street Forecasts
Meta stock began October at $725.93 before recovering during the second week of the month. Shares closed at $742.96 on Monday, gaining 3.38%, as investors reacted to the company’s latest AI developments.
The rally continued on Tuesday, when Meta shares climbed again following the Muse Wonder announcement. Wednesday’s trading brought renewed selling pressure, leaving the stock below its recent highs.
Other analysts have also adjusted their expectations for Meta. Guggenheim raised its target from $700 to $850, while Truist Securities lifted its forecast from $763 to $1,000. BNP Paribas assigned a $885 target as Wall Street assessed Meta’s AI products.
The forecasts differ in their expectations of future earnings and the costs of developing AI services. Investors are waiting to see if revenue generated from subscriptions, advertising, and business products can cover the additional infrastructure costs.
Similar questions have surrounded Nvidia, where recent stock forecasts examined concerns about an AI spending bubble. Meta’s third-quarter earnings, scheduled for October 21, could provide more details about costs and advertising revenue.
Zuckerberg Says Meta Is Reaching the Frontier of AI
Meta CEO Mark Zuckerberg said the company had reached the “frontier of AI” following the release of Muse Wonder. The announcement marked another step in Meta’s efforts to compete with OpenAI and Anthropic.
Meta introduced Muse Wonder and Muse Wonder Full on Monday, adding new capabilities to its growing AI product range. The company reported competitive results in reasoning, coding, and other tasks against models developed by its rivals.
Zuckerberg has continued backing investment in computing infrastructure, research, and AI talent as Meta develops its technology. The company wants these products available across its applications while building paid services for businesses and consumers.
The spending also comes as technology companies seek more computing capacity to support complex models. In recent Nvidia stock price predictions, the focus was on the competition for AI chips arising from the companies’ efforts to develop alternatives to existing processors.
The upcoming quarterly earnings will provide another update for Meta on ad revenue, business spending, and the plans for future investments in AI.
This article is for informational purposes only and does not constitute financial or investment advice.