Pearl
 Bitway
 Pudgy Penguins
 Quantus
 Walrus
 Quant
 Artificial Superintelligence Alliance

MSTR stock has been under severe selling pressure, correcting 62% over the past three months, from its 2025 highs.
As it turns out, the company’s valuation has tanked even below its Bitcoin treasury holdings of $56 billion. This comes despite the BTC price dropping 32% from its all-time high.
MSTR Stock Crash Pushes Market Cap Under Bitcoin Holdings
MSTR stock recently crashed. Market experts now worry about its valuation. They say it trades below the company’s Bitcoin holdings.
Strategy holds 650,000 BTC, worth about $55.9 billion. Its market capitalization is $45.7 billion. This creates a negative net asset value gap of $10.2 billion.
This marks the first sustained NAV inversion in the company’s history. It also signals a sharp reversal of the MSTR stock once enjoyed since starting its Bitcoin accumulation strategy in 2020. Speaking on the development, market expert Shanaka Perera said:
The company recently disclosed the creation of a $1.44 billion cash reserve to cover dividend payments and service obligations. For the first time in five years, management acknowledged that Bitcoin sales could occur as a “last resort.”
For now, Bitcoin is trading $10,000 above the company’s average BTC purchase price of $74,436. However, the hostile market conditions could drag the BTC price even lower.
This could further lead Strategy to forced Bitcoin liquidations to overcome its debt commitment. However, last month, Michael Saylor said that the company is prepared to handle an 80-90% BTC drawdown.
Will MSTR Stock See MSCI Exclusion?
Michael Saylor’s Strategy faces potential exclusion from major equity benchmarks. MSCI is scheduled to review the Strategy’s index eligibility on January 15, 2026. According to JPMorgan estimates, removal from global indices could trigger up to $8.8 billion in forced selling.
In Q3 2025, major institutions reduced their MSTR exposure. BlackRock, Vanguard, Capital International, and JPMorgan sold $5.38 billion worth of shares.
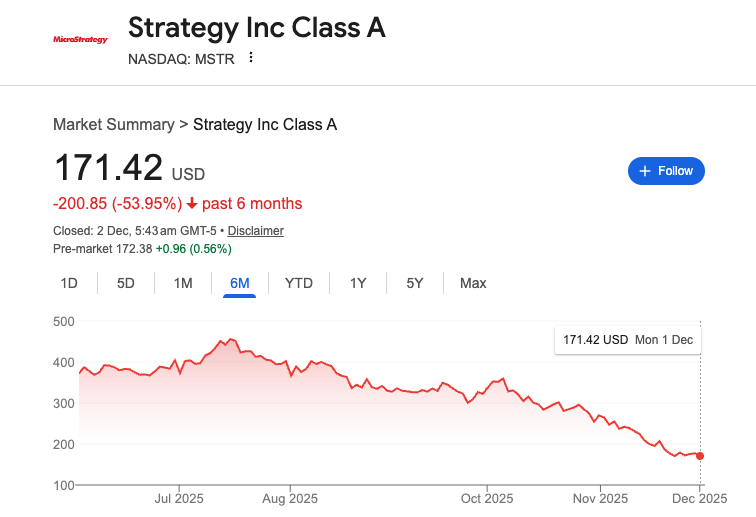
The sell-off comes as the MSTR stock trades 60% below its recent peak. This shows growing concerns over the company’s financial position. Strategy’s balance sheet includes $8.2 billion in debt and $7.8 billion in preferred stock, totalling $16 billion in obligations.
With an average Bitcoin acquisition cost of $74,436, the company remains only about 15% above breakeven. A further decline in Bitcoin’s price could eliminate all unrealized gains accumulated since 2020.
Michael Saylor is the Biggest Con man, says Peter Schiff
As Michael Saylor walks on a tight rope, Bitcoin critic Peter Schiff criticized MSTR’s evolving capital strategy. Schiff says the firm is raising cash by selling equity.
It then uses those proceeds to buy U.S. Treasuries yielding about 4%. At the same time, it is issuing debt and preferred stock at financing costs between 8% and 10%.
Schiff questioned how long investors will continue to view this model as sustainable. He said that the firm’s strategy amounts to a leveraged bet on Bitcoin rather than a viable business framework. In a further sharp criticism of Michael Saylor, Schiff wrote: