IGNITION
 streamoors
 Injective
 NEAR Protocol
 Starknet
 Quantus
 Bittensor

U.S. Treasury news moved back into focus after officials scheduled another long-end debt buyback for Oct. 1. The operation targets nominal coupons maturing between 10 and 20 years. Treasury’s official schedule currently sets the maximum purchase amount at $4 billion or more.
The operation matters because long-term borrowing costs have climbed sharply through late September. Treasury data showed the 10-year yield at 5.26% on Sept. 29. The 30-year rate stood at 5.59%, keeping financial conditions tight across risk assets.
U.S. Treasury News Points to Larger Long-End Buybacks
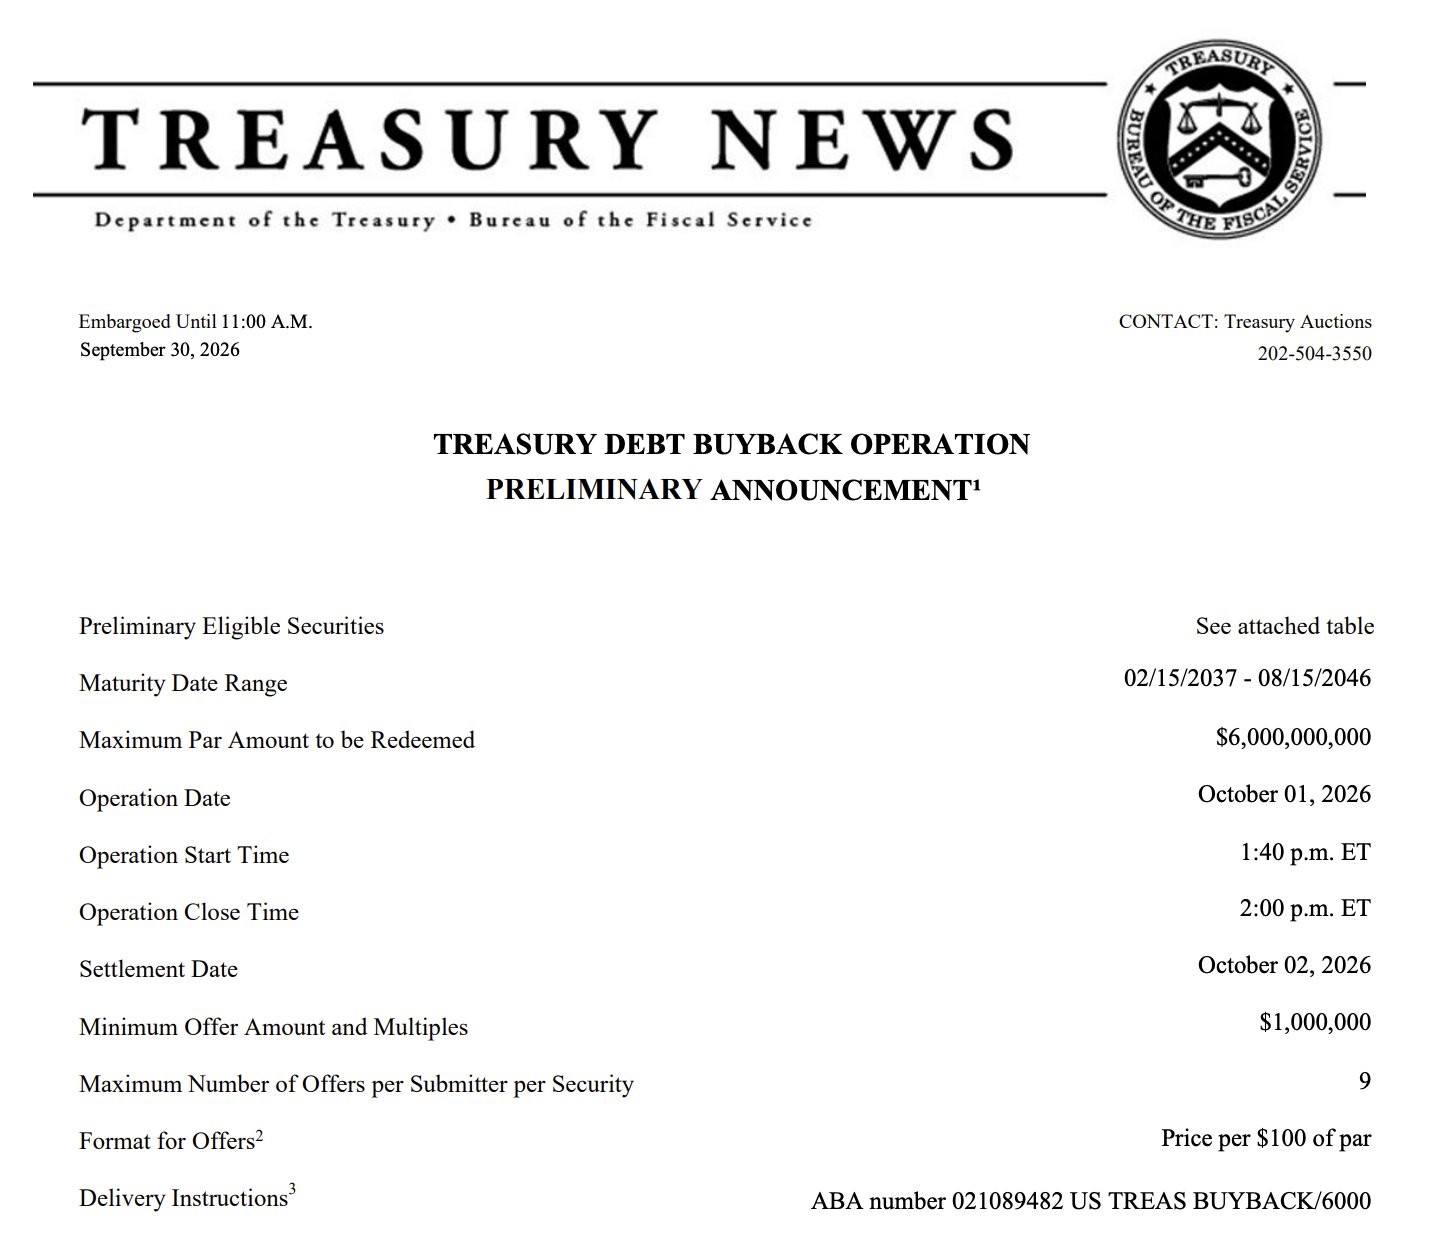
The Treasury’s Sept. 9 schedule set the Oct. 1 operation between 1:40 p.m. and 2:00 p.m. ET. Settlement was scheduled for Oct. 2. Eligible securities mature from Oct. 2, 2036, through Oct. 1, 2046.
The published schedule did not specify a $6 billion maximum for the Oct. 1 operation. Instead, it listed a ceiling of at least $4 billion. Treasury used a $6 billion maximum for its Sept. 10 operation in the same maturity sector.
That distinction matters because several social-media posts described the Oct. 1 ceiling as $6 billion. Treasury’s latest public schedule does not yet confirm that exact figure. An operation-specific announcement could set a higher amount before trading begins.
Treasury had already expanded its longer-dated liquidity support program before the latest operation. An Aug. 19 statement said buybacks would rise from $2 billion to at least $4 billion per operation.
Officials said the larger operations reflected strong market participation in longer-dated sectors. The temporary expansion runs through the current refunding quarter, ending Nov. 4.
U.S. Treasury Yield Pressure Builds Across the Long End
The U.S. Treasury yield curve had already moved higher before the planned buyback. Treasury data placed the 20-year yield at 5.64% on Sept. 29.
The 10-year rate had risen from 4.96% on Sept. 22. The 30-year yield increased from 5.29% over the same period. That move showed continued pressure across longer maturities rather than isolated weakness in one tenor.
Real yields also remained elevated. Treasury data put the 10-year real yield at 2.91% on Sept. 29. The 30-year real yield stood at 3.29%.
The shift also widened the gap between short-term policy rates and long-term market borrowing costs. That divergence can pressure equity valuations and leveraged positions. Crypto traders often track the same rates because higher yields can compete with speculative assets for capital.
Higher real yields raise the return available on inflation-adjusted government debt. That can tighten financial conditions for assets without contractual cash flows, such as Bitcoin.
Bitcoin traded near $83,000 on Sept. 30, according to TradingView market data. The cryptocurrency remained sensitive to rates as traders watched inflation data and Federal Reserve policy expectations.
U.S. Treasury News Does Not Signal Emergency Intervention
Treasury describes these transactions as liquidity support operations, not emergency market intervention. Its official buyback guidance says the program creates predictable opportunities to sell older, off-the-run securities.
Treasury also states that liquidity support buybacks are not designed to address acute market stress. Purchased securities are retired after settlement rather than held for later resale.
The program therefore differs from Federal Reserve quantitative easing. Treasury manages the composition and liquidity of federal debt through these transactions.
The Federal Reserve separately raised its policy range by 25 basis points on Sept. 16. The Federal Open Market Committee set the federal funds target at 3.75% to 4.00%.
The committee approved that decision unanimously, citing elevated inflation and its 2% inflation objective. That policy backdrop helps explain why longer-dated yields remain central to broader market pricing.
U.S. Treasury Yield Moves Keep Crypto Traders Watching Rates
For crypto markets, the immediate issue is the direction of long-term yields after the Oct. 1 operation. A buyback can improve trading conditions in less-liquid Treasury securities without directly lowering benchmark yields.
Treasury guidance also allows officials to purchase less than the announced maximum. Final amounts depend on submitted offers and Treasury’s evaluation of those bids.
That means the accepted amount will provide more information than the headline ceiling alone. Traders can also compare the result with the Sept. 10 operation and later long-end transactions.
The next verified milestone arrives on Oct. 1, when Treasury conducts the 10- to 20-year buyback. Results will show how much debt officials accepted and at what prices.