Zylo Ecosystem
 Pearl
 Walrus
 Derive
 Quantus
 Aerodrome Finance
 Sui

Nvidia stock price has pulled back and moved into a correction in the past few days, moving from the year-to-date high of $184 to $167 today. This crash is mostly because of the rising competition from companies like Broadcom and Alibaba, and its China woes.
Nvidia Stock Price Has Become a Bargain
Nvidia, the biggest company in the world with a market capitalization of over $4.3 trillion, has become a bargain.
Data compiled by SeekingAlpha shows that its forward price-to-earnings (P/E) ratio has dropped to 38 in the past few weeks as its stock dropped.
The forward PE multiple is a bit higher than the technology sector median of 31. However, the multiple is much lower than Nvidia’s five-year average of 60.
The PE multiple looks at a company’s stock price concerning its earnings, with a higher figure showing that it is overvalued. However, the multiple’s main limitation is that it does not include a company’s growth metric.
To solve this limitation, investors use the price-to-earnings-to-growth (PEG) ratio. In this case, Nvidia has a forward PEG ratio of 0.99, much lower than the sector median of 1.82 and its five-year average of 1.72.
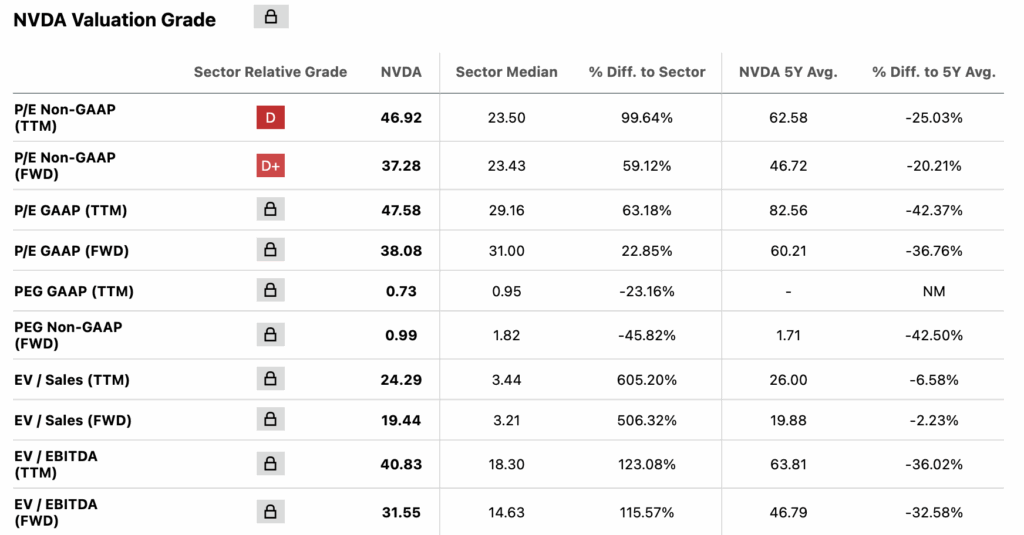
Other valuation metrics show that the Nvidia stock price is also getting cheap. For example, the forward enterprise value (EV) to EBITDA multiple has dropped to 31, down from its five-year multiple of 39.
Meanwhile, the company is also a bargain using the rule-of-40 multiple that looks at a company’s revenue growth and profit margins. In its case, it has a forward revenue estimate of 58% and a net profit margin of 52%, giving it a rule-of-40 multiple of 110%, meaning it balances its growth and profitability well.
However, the rule-of-40 multiple mostly applies to software-as-a-service (SaaS) companies, like Salesforce and Adobe.
Broadcom and Alibaba Competition Concerns
There are three main reasons why the Nvidia stock price has plunged into atechnical correction in the past few days. First, there are concerns that the company has lost China, the biggest semiconductor market globally. It recently paused shipping its H20 chips there and has not factored any sales from the country into its annual guidance.
Second, in its last earnings report, Nvidia warned that it was starting to see slow revenue growth. Most notably, it said that almost 50% of its revenue came from a handful of hyperscaler companies.
While their names are private, analysts believe they are big names like Meta Platforms, Amazon, Google, and Microsoft. Last week, Meta Platforms pledged to continue boosting its AI data center spending in the next few years. Still, customer concentration is a big risk for any company.
Third, Alibaba is said to have built a highly advanced chip that will compete with Nvidia’s. Most importantly, OpenAI has entered into a partnership with Broadcom for custom chips.
Therefore, the fear is that the company’s moat in the GPU industry could drop in the coming months.
NVDA Stock Price Technical Analysis
On the positive side, the NVDA stock price has formed a highly bullish chart pattern that may push it much higher in the coming weeks. It has formed a bullish flag pattern on the daily timeframe chart.
This pattern is made up of a vertical line and a horizontal channel whose support and resistance levels are at $170 and $184. The stock has also remained above the 50-day moving average, and is at the top of the range of the Murrey Math Lines tool.
Therefore, the stock will likely have a strong bullish breakout, initially to the key resistance level at $184, the highest point this year. A move above that resistance will point to more gains, potentially to the extreme overshoot level of $225.
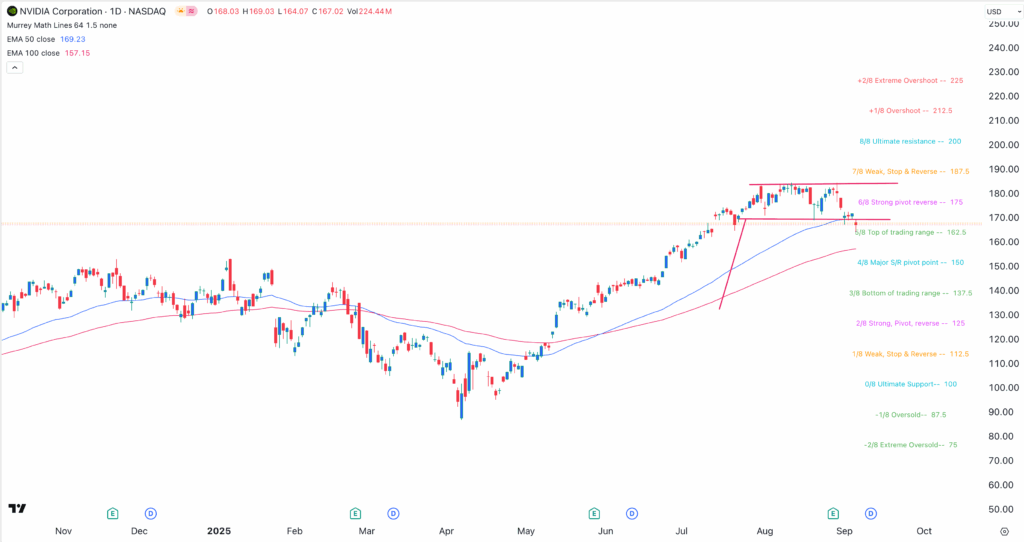
The bullish Nvidia share price forecast will become invalid if it drops below the major support and resistance pivot point of the Murrey Math Lines at $150. Moving below that level will point to more downsides.