Bitcoin
 Pearl
 Quantus
 NEAR Protocol
 Ondo
 Walrus
 Pudgy Penguins

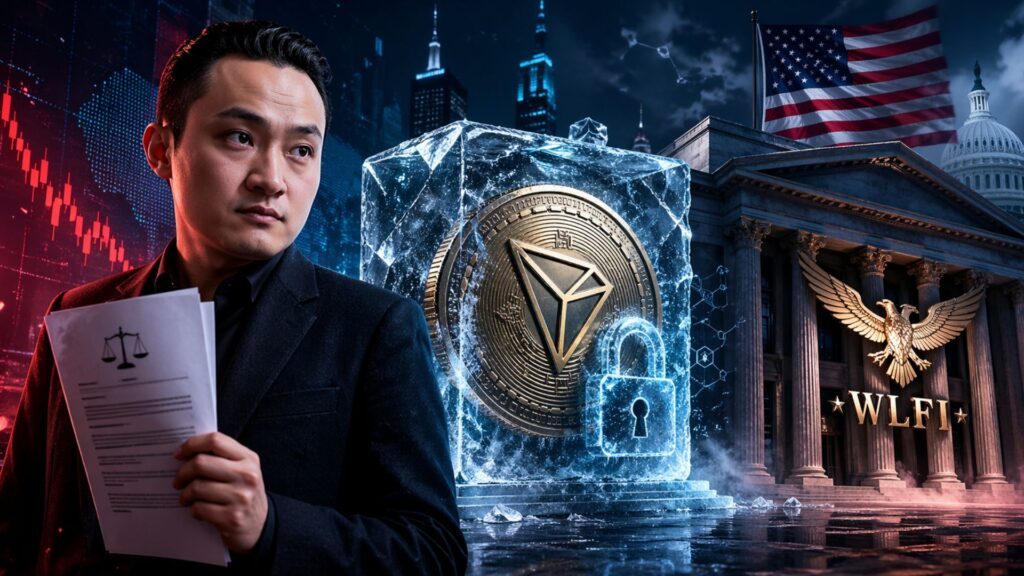
Justin Sun has filed a lawsuit in California federal court against World Liberty Financial, the Trump-backed crypto venture, after a dispute over frozen WLFI tokens and governance rights. Sun said the project froze his holdings without justification, blocked him from voting, and threatened to destroy the tokens through a burn process. The crypto news reported that Sun invested $45 million in the project starting in late 2024, while earlier public reporting and Sun’s own statements have tied his overall exposure to about $75 million.
Justin Sun Lawsuit Targets Token Freeze and Voting Restrictions
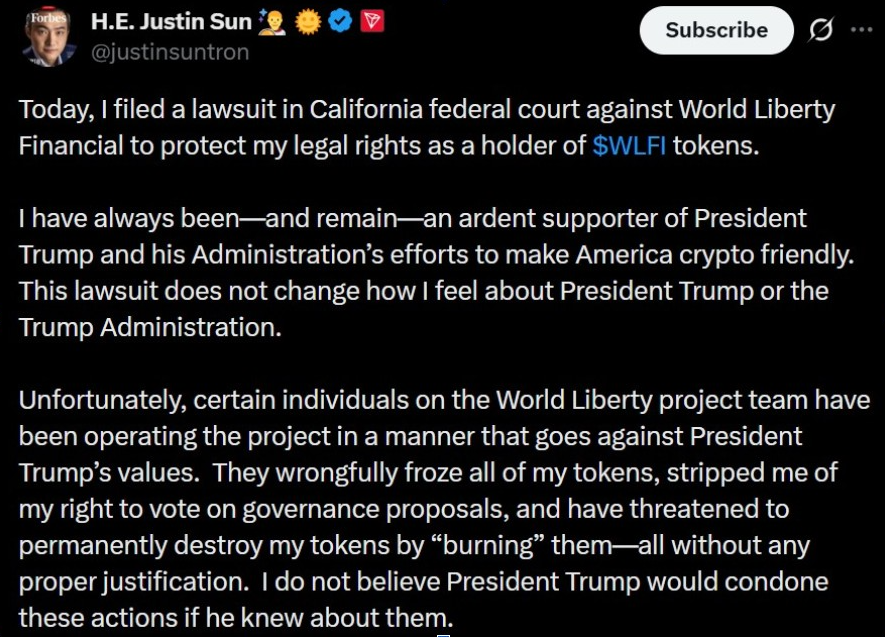
Justin Sun announced the legal action on April 22 and framed it as a move to protect his rights as a WLFI holder. In his public statement, he said World Liberty froze all his tokens, revoked his voting rights, and left him unable to participate in governance decisions related to the project. According to the crypto news, Sun asked the court to stop the venture from seizing, burning, or otherwise restricting the tokens.
The court filing adds another layer to a dispute that had already spilled into public view this month. In last week’s crypto news, Sun accused World Liberty of using a hidden blacklist function in its smart contracts, which he said gave the team power to freeze wallets and reallocate tokens. World Liberty had rejected those accusations and said its disclosures already allowed wallet freezes in cases tied to risky or unlawful activity.
Dispute Centers on April 15 Governance Proposal
The immediate clash also ties back to a governance proposal that World Liberty published on April 15. The plan would keep 80% of early investor tokens from trading until 2030, using a two-year cliff followed by a two-year vesting schedule. The proposal also included a 10% burn tied to adviser holdings, which added pressure on early backers who opposed the plan.
Justin Sun said he opposed that proposal, but could not vote on it because the project had already frozen his tokens. In his statement, he said holders who did not actively accept the terms faced indefinite lockups, while adviser tokens faced a permanent 10% burn. He argued that the structure punished dissenting holders and blocked fair participation in governance.
Justin Sun Backs Trump and Blames Project Operators
Even as he sued the Trump-linked venture, Justin Sun separated the dispute from his view of President Donald Trump and the administration’s crypto stance. In his X post, the Tron founder said,
“I have always been and remain an ardent supporter of President Trump and his Administration’s efforts to make America crypto-friendly. This lawsuit does not change how I feel about President Trump or the Trump Administration. Unfortunately, certain individuals on the World Liberty Project team have been operating the project in a manner that goes against President Trump’s values.”
World Liberty has drawn attention for its close ties to the Trump family. The company has proposed token rules that would also affect Trump family holdings, while public criticism from investors has focused on governance, transparency, and insider economics.
The lawsuit arrives as World Liberty faces wider scrutiny over its finances and structure. The crypto news reported that Sun claimed the project is near collapse, has pulled liquidity from USD1 pools, and lacks sufficient reserves to support redemptions. The venture planned to direct much of the token sale proceeds to insiders, a claim that adds to pressure around the project’s governance model.