streamoors
 IGNITION
 no crying in the casino
 Sword Inu
 Altai the Tiger
 NEAR Protocol
 Quantus

Nvidia stock price has rebounded in the past few days, moving from this month’s low of $172 to the current $189. Still, it remains significantly lower than the all-time high, as concerns about its growth trajectory persist. This article explores some of the top reasons why the NVDA share price is on the verge of a strong bullish breakout in the coming weeks.
Nvidia Stock Technicals Points to a Rebound
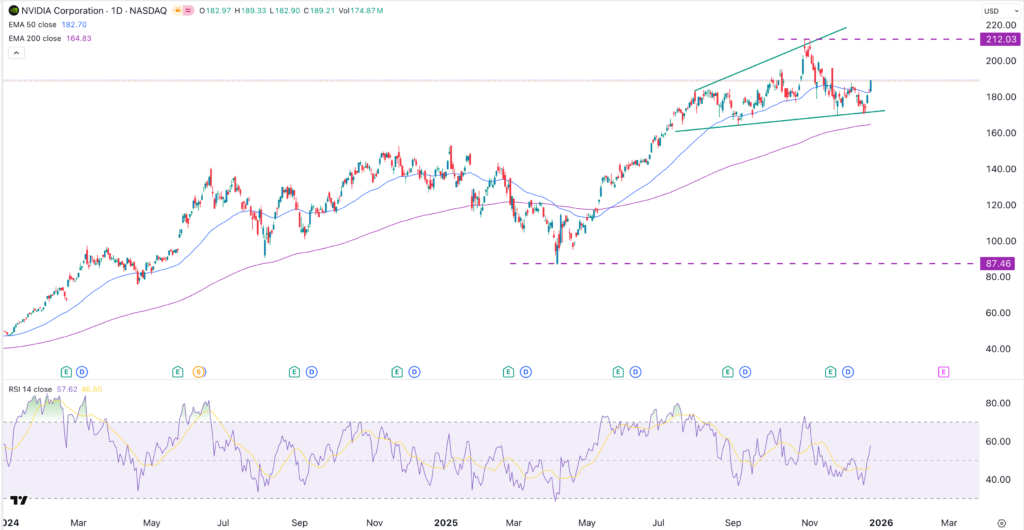
The daily timeframe chart reveals that the Nvidia stock price has bounced back from this month’s low of $172 to the current $189.
A closer look reveals that it has formed a rising broadening wedge pattern, comprising two ascending and diverging trendlines. It is a common bullish continuation sign.
The stock has also jumped above the 50-day Exponential Moving Average (EMA) and is now about to move above the Strong, Pivot, and Reverse levels of the Murrey Math Lines tool.
Additionally, the Relative Strength Index (RSI) has moved above the neutral level of 50, indicating that it is gaining momentum.
Therefore, the most likely scenario is that the NVDA stock price continues to rise, potentially reaching the year-to-date high of $212. A move above that level will signal further gains, potentially reaching the psychological level at $250.
The bullish Nvidia stock price forecast will become invalid if it moves below the lower side of the megaphone pattern. Such a move will invalidate the bullish outlook and point to more downside, potentially to the 200-day moving average level at $164.83.
Analysts are Still Bullish on the NVDA Stock
The other main reason why the Nvidia stock price may have more upside is that analysts believe it has more upside in the coming months.
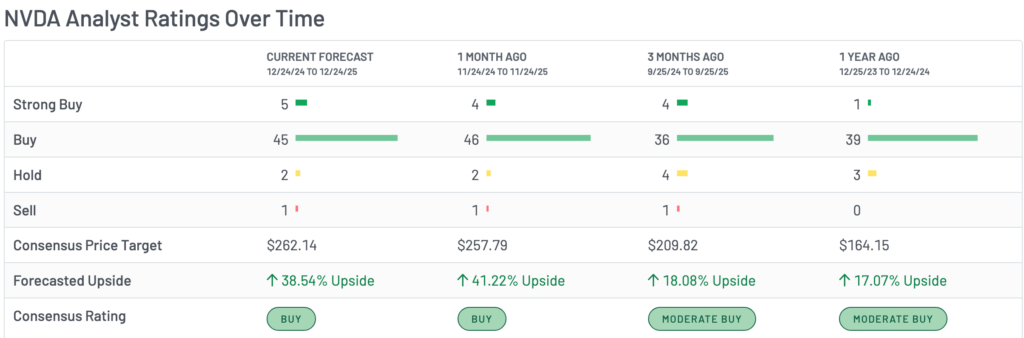
Data compiled by MarketBeat indicates that the average target price among investors is $262, which is approximately 38% above the current level. The most optimistic analyst is Mark Lipacis of Evercore ISI, who believes that it may jump to $352.
Most importantly, as the chart below shows, analysts have been boosting their NVDA stock price targets. Their target was $164 12 months ago and $252 a month ago, a sign that analysts are becoming more optimistic.
Most analysts believe that Nvidia has a strong market share in the chip industry that companies like Google, Moore Threads, Cambricon, and MetaX Integrated Circuits will find it hard to disrupt.
For one, Nvidia has thrived despite the rising competition from AMD, a company that has made highly competitive chips for data centers.
Nvidia Growth to Continue
Wall Street analysts are highly upbeat about Nvidia’s growth trajectory in the coming year, a move that will help to justify its valuation.
The average estimate among analysts is that the company’s fourth-quarter revenue will be $65.7 billion, a 66% surge from the same period last year.
Also, analysts expect the company’s revenue in the first quarter of next year to come in at $70 billion, a 60% increase. The annual revenue growth for the current year and 2026 are expected to be 63% and 49%, respectively.
The company may report stronger results than these as it has always done in the past. Additionally, these estimates don’t account for the fact that the company is preparing to start selling its H200 chips in China starting from February next year.
According to Reuters, the company plans to sell between 5,000 and 10,000 chip modules, which is equivalent to between 40,000 and 80,000 chips.
Nvidia Stock is Cheap
Finally, there are signs that Nvidia stock is undervalued despite its $4.6 trillion market capitalization. It has a forward price-to-earnings ratio of 40.3 and a forward PEG ratio of 1.08. These numbers are much lower than the five-year averages of 50 and 1.62, respectively.
The company is also more affordable based on the rule-of-40 valuation metric, as its forward revenue growth is 63% and its net profit margin is 53%, resulting in a multiple of 116%.