Zerebro
 Bitcoin
 Quantus
 Pearl
 Starknet
 ZKsync
 NEAR Protocol

Coinbase stock price has plunged this month after its recent results pointed to major red flags, such as slow revenue growth and higher costs. COIN has dropped to $300, down 30% from the year-to-date high. Here are the top 4 headwinds that may affect its recovery.
Coinbase at Risk as Competition Rises
One of the biggest headwinds that Coinbase stock is facing is that competition in the United States and other countries is rising. CoinMarketCap data shows that Coinbase’s spot exchange handled $2.2 billion in transactions in the last 24 hours.
In contrast, Binance handled $16.7 billion, while Bybit, Bitget, and MEXC handled over $3 billion in the same period.
These companies do well because most of their focus on the international market. While Coinbase is available globally, most of its business is in the United States, where it has a large market share.
The risk, however, is that its business in the US is facing headwinds. For example, the most recent results showed that Coinbase’s revenue rose by just 3% in the second quarter.
In contrast, Kraken’s revenue jumped by 18% in the same period to $412 million. Robinhood’s crypto revenue more than doubled in the same period.
Competition in the US will keep rising as SoFi will relaunch its crypto business later this year. Also, OKX has relaunched its US business, and Binance US is considering moving back to the US.
This competition will likely push Coinbase to slash its high fees to attract new customers and retain the existing ones.
Coinbase Costs are Jumping
The other potential headwind for the Coinbase stock is that its costs continue rising, likely affecting its profitability. As the chart below shows, Coinbase had total operating expenses of $1.52 billion in the last quarter, a $193 million increase from the previous quarter and $415 million higher than in Q2’24. The share of transaction expenses to revenue rose from 14% in Q2’24 to 17% in Q2’25.
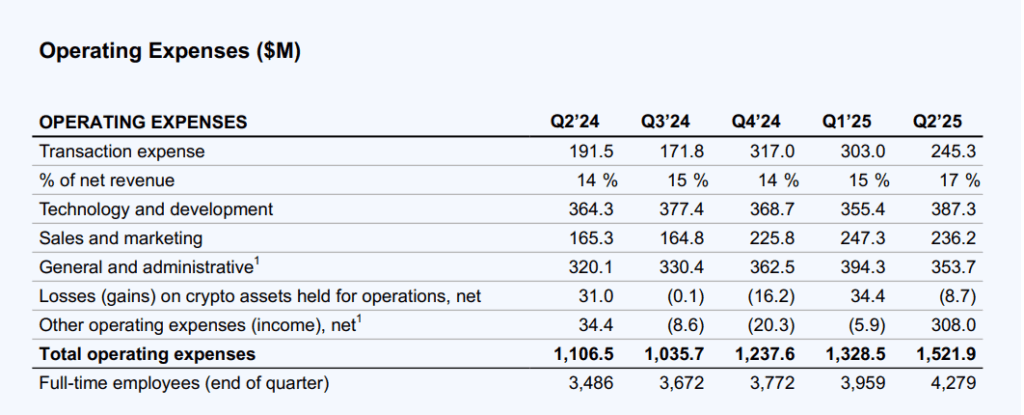
The rising costs, while good in the long term, will likely hurt the company’s short-term profitability, which will hurt its stock price.
Coinbase Stock Price is at Risk Because of its Valuation
Additionally, there are concerns that the Coinbase stock price is highly overvalued. Data shows that the company trades at 40x forward earnings multiple, higher than the financial sector median of 10.7.
It is understandable why Coinbase share price is attracting a higher valuation multiple. It is the biggest crypto exchange in the US and continually expands its business into the subscription and services industry.
For example, it has become the biggest crypto custodian with over $265 billion in assets under custody. It also runs the biggest layer-1 network, which has become popular among developers and users.
However, the current valuation, while lower than Robinhood’s 60x multiple, is higher than its revenue growth. Yahoo Finance data shows that the average revenue estimate for the year is $7.38 billion, reflecting a 12.38% annual growth rate.
Coinbase Stock Technicals Point to a Crash to $260
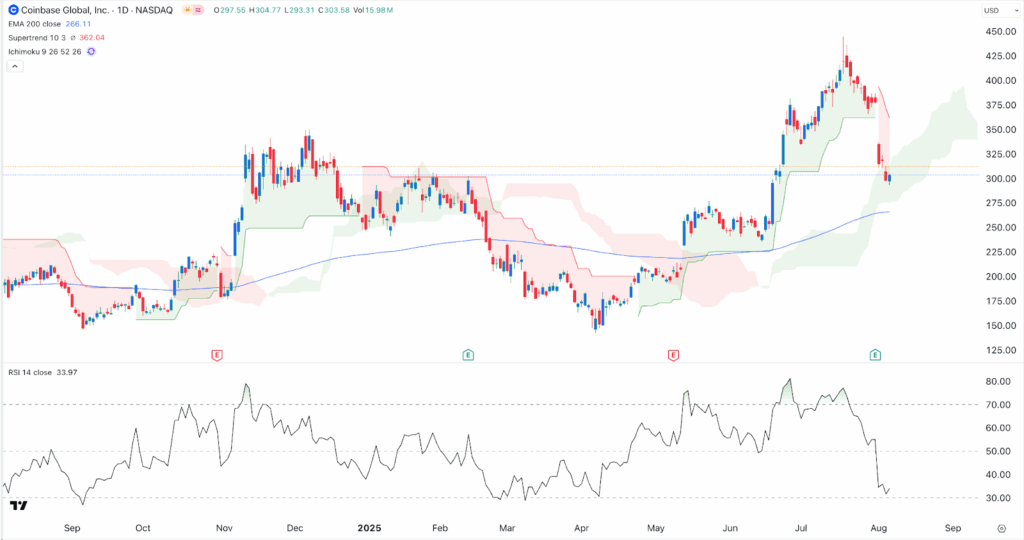
The daily chart reveals that Coinbase’s stock price has been in a strong downtrend since its quarterly earnings. It has moved below the Supertrend indicator and is about to crash below the Ichimoku cloud. Also, the Relative Strength Index has not yet reached the oversold level.
It remains above the 200-day moving average at $265, where it may move to before bouncing back. A drop below that moving average will point to more downside.
Summary
Coinbase stock price has many tailwinds that may drive its stock higher over time. It is growing its services and subscriptions business, has partnerships with top companies like BlackRock and Grayscale, and has a large market share in the US.
It also has a strong balance sheet with over $9 billion in cash. However, the headwinds mentioned in this article may drag the stock over time.