astronaut
 Pearl
 Zylo Ecosystem
 Bitcoin
 Bitway
 NEAR Protocol
 Zcash
Key Insights:
- Bitcoin 3-month average volumes approached ATHs as long options tripled.
- The 180-day call-put skew on Deribit declined to -0.42, a record low since June 2023.
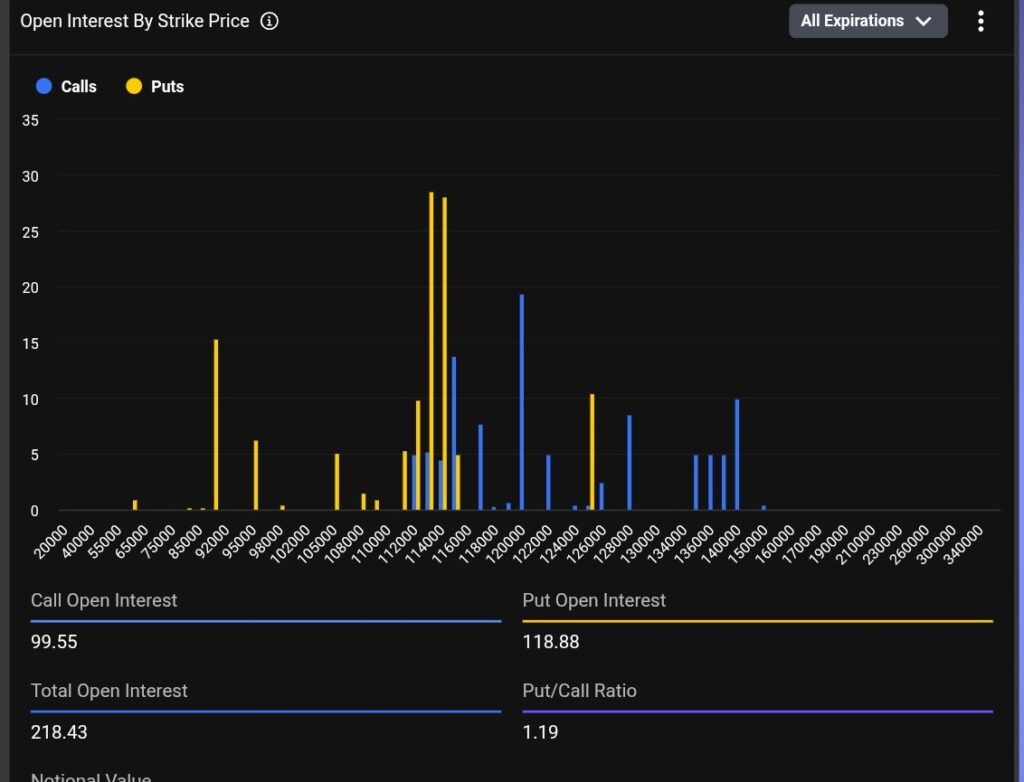
- The Put open interest reading was now 118.88, while the Call OI reading was 99.55.
The cryptocurrency markets were generally uncertain as Bitcoin (BTC) led the bleeding. Cryptocurrency capitalization was down about 1% in the last 24 hours as per CoinMarketCap. Still, more sell-side risk was building up.
Stocks were facing the same fate. AI stocks like Nvidia (NVDA), which have been outperforming the markets, were also in the red. Nasdaq and S&P 500 were down as Wall Street rushed to put more pressure on the sales.
The Jackson Hole event talks and odds of Fed ‘NOT’ cutting rates taking a U-turn added more sell-side risk on where the markets were headed. However, the sentiment was mixed for both crypto and stocks.
Bitcoin Options: Momentum Fading As Sell-off Risk Escalates
According to Deribit data, Bitcoin options momentum was fading as put options gained more interest. The 180-day skew declined to negative 0.42, a record value since 2023. The upcoming events and heightened profit-taking in the crypto and stock markets added sell-off risk.
The Put options open interest (OI) reading was now at 118.88. The Call Open interest was at 99.55. From the Deribit chart, a cluster of Put options stood between $116,000 and $112,000, suggesting that more sales were lined up for execution. Below the $100,000 level, the largest short position was at $90,000.
For call options, the most significant optimistic level was at $140,000, with these options expiring in late September.
Bitcoin futures composite index flipped back to positive, giving a contrary opinion. The sentiment had been in red for the last five days as per data from the author of CryptoQuant on X (formerly Twitter), Darkfost. Historically, similar sentiments turned the markets bullish as seen in August 2024.
Generally, the Put/Call ratio of 1.19 weighted more on decline. The sentiment across the socials also shifted to neutral. This is after long periods of a market controlled by greed.
Call Options Triple But Bull Score Index Switches
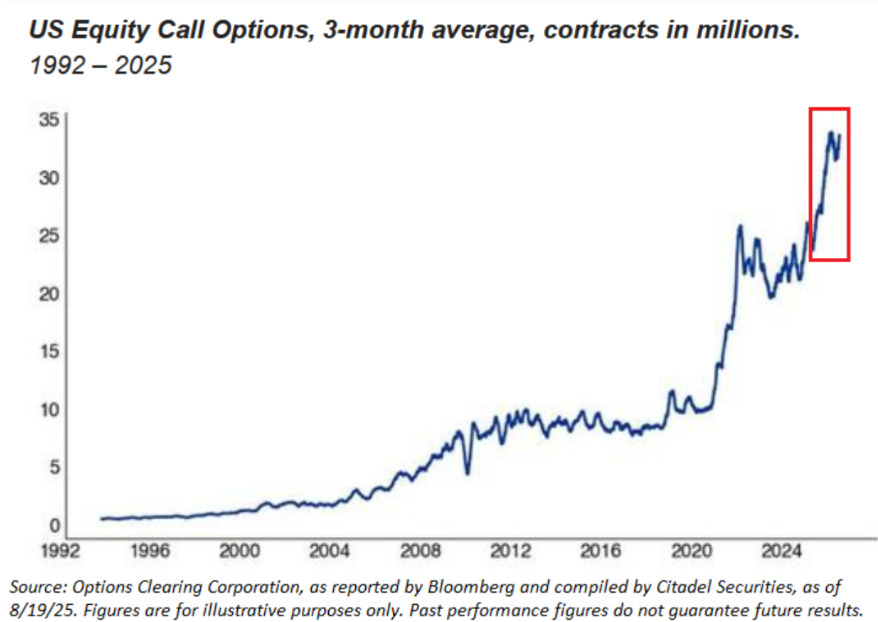
The Kobeissi Letter on X further reiterated that the options market activity was approaching the ATH of 34 million contracts. The number of call options has tripled over the last five years despite the recent data starting to fade. The interest in trading options rose as total contracts hit 71 million. The annual average daily volume stood at 58 million.
The Bull Score Index has cooled down to neutral levels, supporting a further drop. The softening of the Bull Index indicated that prices of Bitcoin and stock options could drop further.
Risk For Further Sell-off: Jackson Hole Event and Odds of Fed ‘NOT Cutting’ Rates
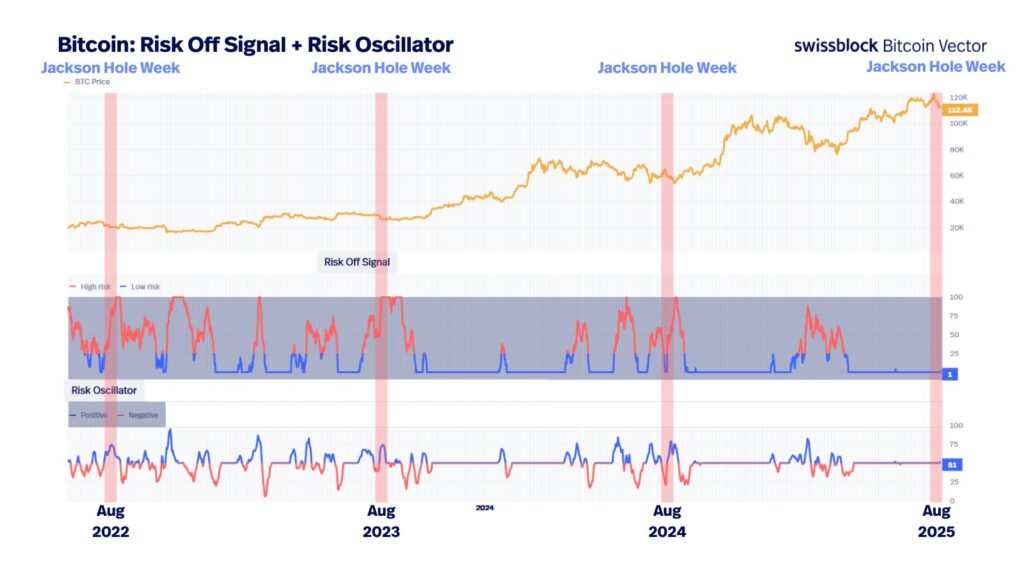
The Jackson Hole event could also ignite further sell-off. However, it’s historically different this time. Previously, it coincided with the risk indicators coming off imbalance. This time, the indicators were off stability.
This comes as the odds of the Fed ‘NOT’ cutting rates in September took a U-turn. The potential rose from 25% to 34%, the highest in August. In the heat of the moment, the DOJ is calling for Jerome Powell to oust Fed Governor Lisa Cook due to mortgage fraud allegations.
Still, there were some positives from the analysts. Arthur Hayes said he would overleverage on longs as he anticipated the rates to be cut. Speaking to Crypto Banter, the CEO of BitMEX was placing his bets on Trump’s principles. He noted that Trump had other ways to energize the market, even if the Fed did not cut rates.
In summary, the Bitcoin options market was facing fading momentum in calls while puts were increasing in concentration. Still, there were bullish opinions with a lot of feeling that Fed rate cuts could spark market volatility.