
 streamoors
 Celestia
 IGNITION
 Injective
 Pudgy Penguins
 LayerZero
 Quantus

As 2025 comes to an end, U.S. stock markets are closing the year on a strong note. The S&P 500 reached a new record on December 23, marking four straight days of gains.
The Nasdaq and Dow also advanced, supported by upbeat economic data and strong performance in technology and commodities.
Despite weaker consumer confidence, investors remain optimistic. Seasonal factors like the “Santa Claus rally” add to the momentum, setting the stage for a positive start to 2026.
Market Gains Ahead of Holidays
On December 23, the S&P 500 closed at 6,909.79, up 31.30 points or 0.46%. The Nasdaq Composite rose 133.02 points or 0.57% to 23,561.84. The Dow Jones Industrial Average added 79.73 points or 0.16% to finish at 48,442.41.
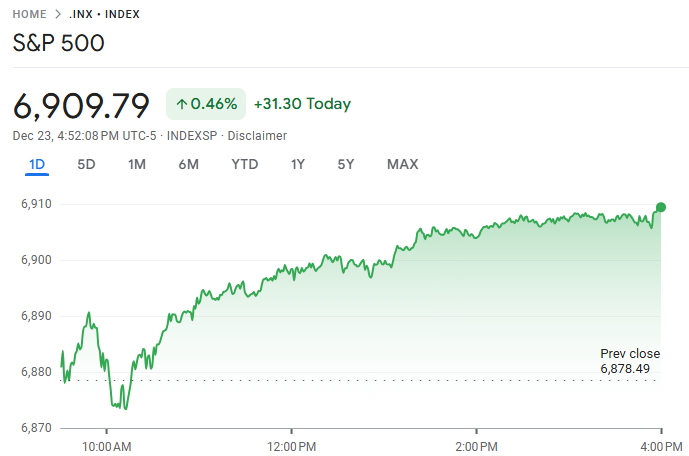
Trading volume was lighter than average, typical for the pre‑holiday period. Investors digested key reports while markets extended their winning streak. Early December 24 trading showed modest gains, with the S&P 500 edging up 0.06% to about 6,914 intraday.
Economic Data and Consumer Trends
The main driver was a stronger revision to third‑quarter GDP growth. The U.S. economy expanded at an annualized rate of 4.3%, beating forecasts of 3.3%. This was the fastest pace in two years. Consumer spending grew at a 3.5% annual rate, up from 2.5% in the prior quarter.
Exports rebounded, surging 8.8% after contracting in Q2. Consumer spending accounts for approximately 70% of U.S. economic activity, demonstrating resilience despite inflation and policy uncertainty.
Not all data was positive. Consumer confidence fell for the fifth month. The Conference Board index dropped to 89.1 in December from 92.9 in November. Four of the index’s five components weakened. High prices, tariff risks, and a cooling labor market weighed on sentiment.
Household income, adjusted for inflation, remained stagnant, and the saving rate declined. Still, Americans continued to spend, fueling growth but raising questions about sustainability in 2026.
Sector Moves and Year‑End Outlook
Technology and growth stocks led the rally. Nvidia climbed 3%, giving the biggest boost to the S&P 500. Amazon, Alphabet, and Broadcom each gained more than 1%. Higher bond yields after the GDP data favored growth names over value stocks. Commodities also rallied.
Gold topped $4,500 per ounce. Silver exceeded $70. Copper hit a record above $12,000 per ton. Mining firms benefited, with Freeport‑McMoRan rising 2.5%. On the downside, ServiceNow fell 1.5% after announcing a $7.75 billion acquisition.
As of December 23, index performance showed strong year-to-date gains. The S&P 500 rose by approximately 45%. The Nasdaq gained about 55%. The Dow rose about 28%. Seasonal trends added support.
The “Santa Claus rally” has historically delivered average S&P 500 returns of 1.3% since 1950, occurring in 79% of years.
Analysts noted an improvement in market breadth and a rotation toward cyclical sectors. LPL Financial’s Adam Turnquist said a close above December’s high could push the index toward 7,000.
Looking ahead, Wall Street’s 2025 performance positions major indexes for a third straight annual advance. Risks persist, including tariffs and the Federal Reserve’s policy. Still, the holiday rally caps a remarkable year, underscoring the enduring appeal of U.S. markets.



